Release Notes
Last updated: 2026-09-27
Feedback
Do not hesitate to provide us with feedback using the contact form.
Roadmap
- Q4 2026 - Hedging for benchmarks
- Q4 2026 - Market, Credit & Liquidity Risk
- Q4 2026 - Expected returns according to Black-Litterman
- Additional coverage for derivatives
- Portfolio book monitoring
- UI for mass rebalancing (currently only available on the API)
- Suggested instruments for diversification
- Additional coverage for structured products
- AI based country exposure
- Portfolio monitoring: Unusual Price Action
2026-09-27 Release 7.0
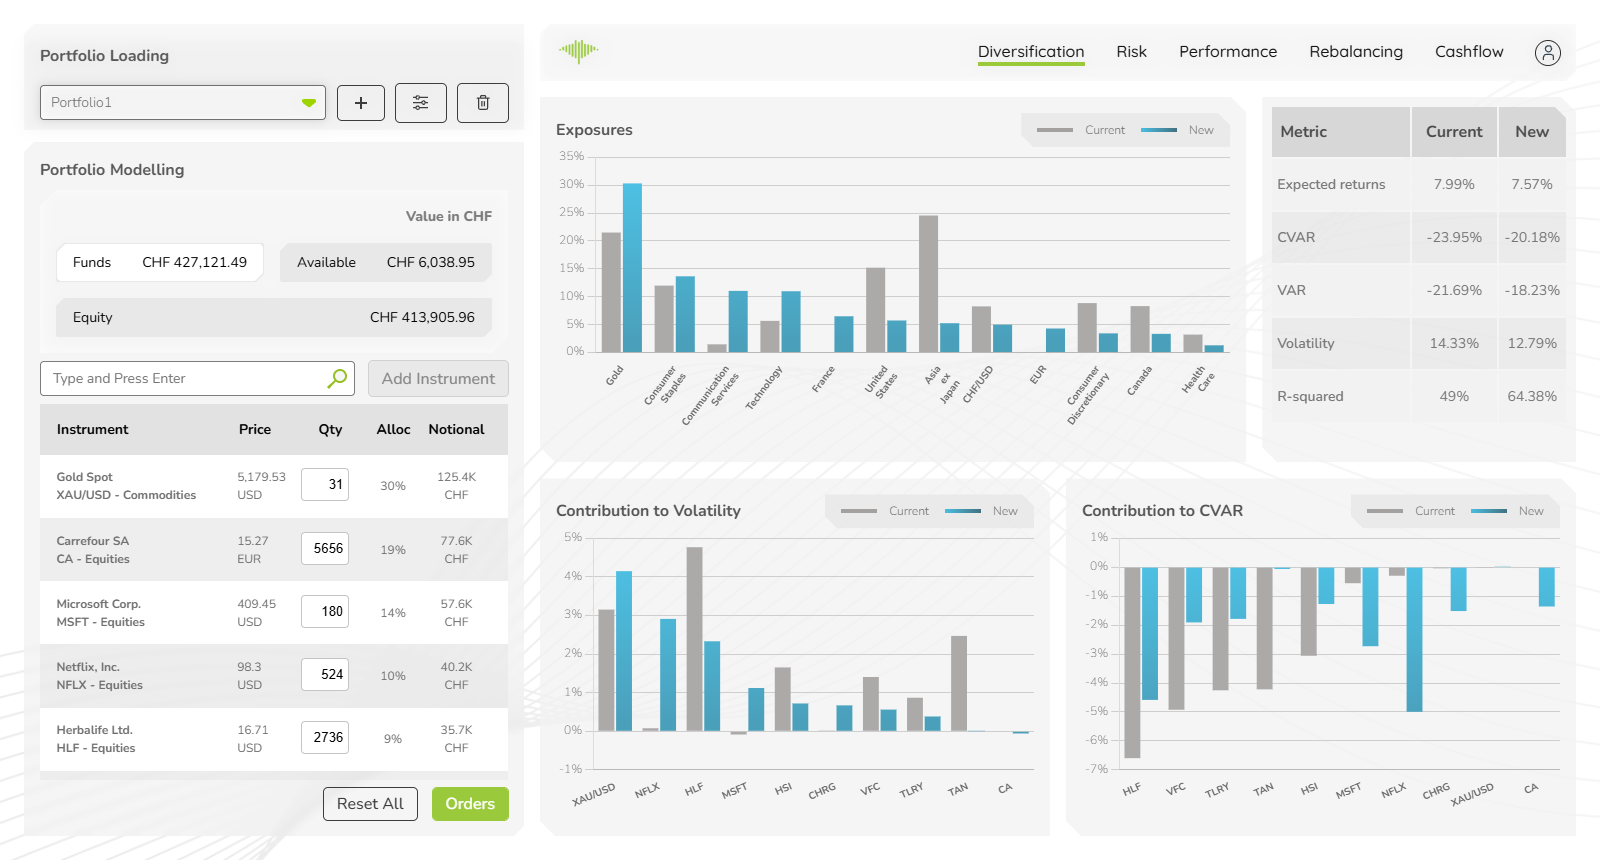
MantaWealth - Revised Diversification screen
- UX improvements, including easier-to-read headline figures (expected return, volatility, and CVaR with VaR), and reworked diversification chart.
- A new Largest risk shifts panel lists only the holdings whose risk the change moves, split into less and more risk.
- A new Risk by holding table puts each holding's contribution to CVaR and to volatility side by side.
- A new Risk kept metric shows how much of a holding's own tail risk (CVaR) is left once it sits in the portfolio: 100% means the rest of the portfolio offsets none of it, and below 0% marks a hedge. For the whole portfolio, it shows how much of its holdings' combined risk remains after diversification.
- A Quality of Analysis line reports how much of the portfolio's risk is modelled and how much is explained by common risk factors.
See Diversification for a full description.
- MantaWealth / MantaAPI - Performance Attribution Analysis: performance enhancements.
- MantaAPI - Credit Risk: preparatory work for the upcoming Credit Risk analytics.
2026-08-16 Release 6.5
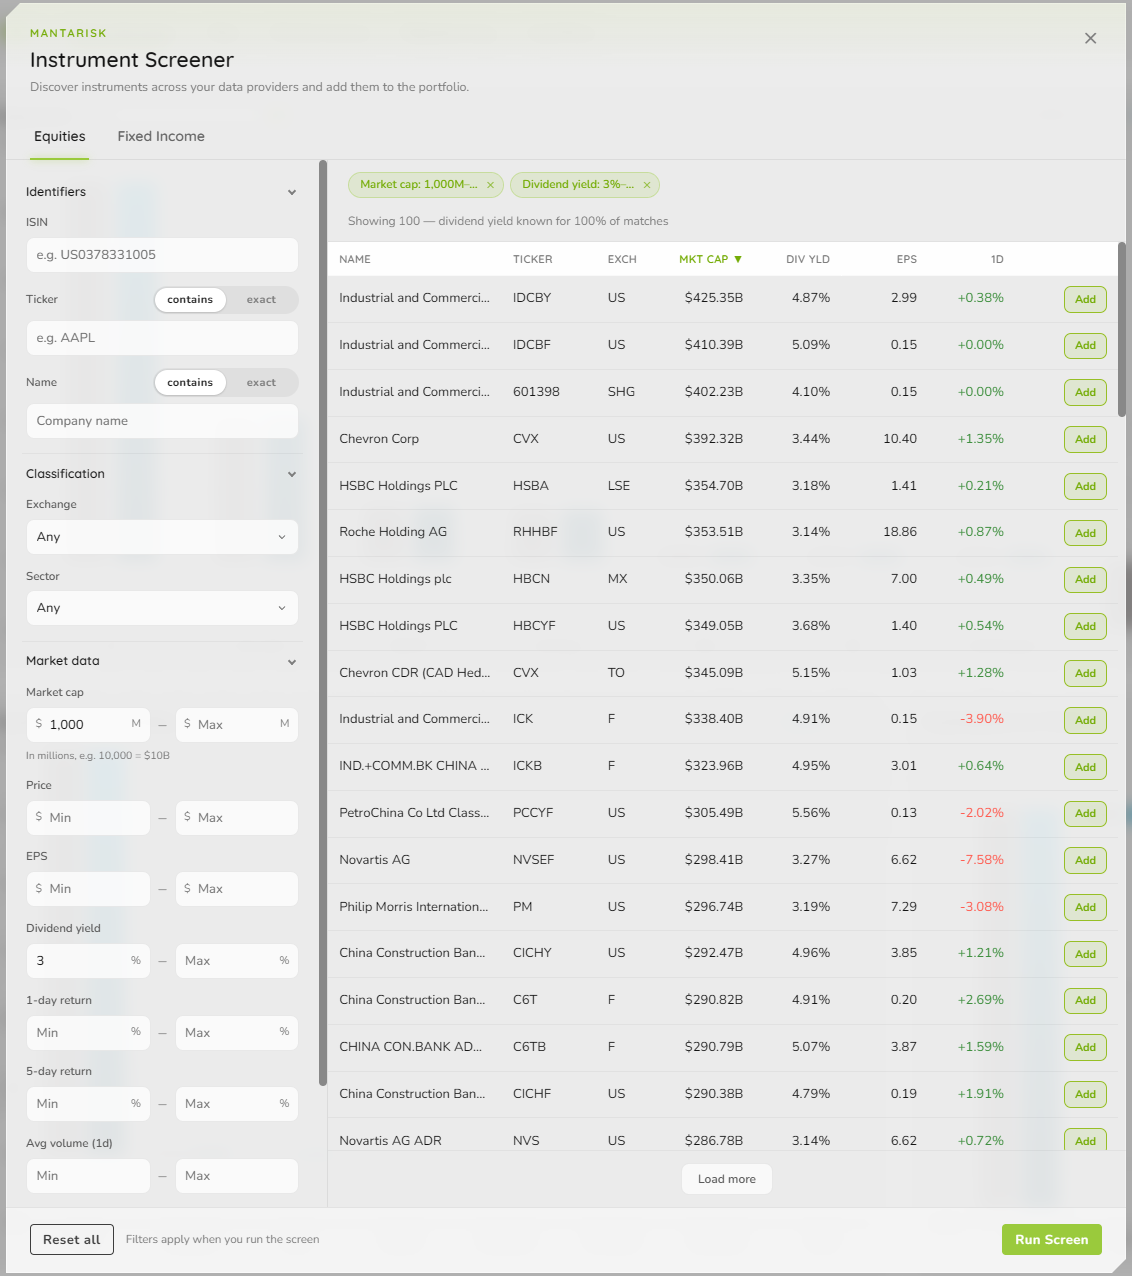
MantaWealth - Instrument Screener
- A new Screener button next to the instrument search field opens an Equities and Fixed Income instrument screener.
- Equities screen on exchange, sector, market cap, price, EPS, dividend yield, 1- and 5-day return, average volume, and pre-computed signals (new 50/200-day highs and lows, analyst target, book value).
- Fixed Income screens on issuer sector, geography, country, region, industry, coupon type, currency, face value, yield, duration, coupon rate, outstanding volume and maturity — and default to bonds still available to buy.
- Results are sortable on any column, and any match can be added straight into the portfolio.
2026-08-09 Release 6.4
- MantaWealth / MantaAPI - Performance & stability: broad performance improvements and stability hardening across the platform.
- MantaAPI - Reporting endpoint: new options:
- Section selection: any of the report's sections — portfolio composition, factor exposure, risk analytics, stress testing, performance analysis and cashflow forecast — can now be individually included or omitted per report.
- Before/after comparison: reports can now be generated in a comparison mode that presents a portfolio's current holdings alongside a proposed rebalanced version — composition, factor exposure, risk metrics, stress testing and cashflow forecast shown side by side.
- MantaWealth / MantaAPI - Performance Attribution methodology update: the PAA CAPM curve is now built purely from historical data. Synthetic data reconstruction has been removed from the curve calculation, so attribution results reflect only genuine observed prices.
2026-06-24 Release 6.0
MantaWealth / MantaAPI - Methodology update: VaR & CVaR
- VaR and CVaR are now computed on demeaned returns — the historical mean is subtracted before estimating the loss quantile — so tail risk is measured independently of expected return (Rockafellar–Uryasev–Zabarankin, 2006).
- Portfolios with a positive historical drift will therefore show higher CVaR/VaR; those with a negative drift, lower.
- CVaR and VaR (incl. contributions) are no longer published above a monthly horizon (quarter, YTD, year), where time-scaling is unreliable under fat tails — long-horizon and crisis tail risk is covered by our stress-testing / scenario analysis instead.
2026-05-17 Release 5.5
- MantaWealth - Private Asset Management: private assets are now managed directly from the MantaWealth front-end, bringing the proxy-based coverage previously available on MantaAPI into the UI.
- MantaWealth / MantaAPI - Report Configuration: organisation-level defaults for PDF Investment Proposals (co-branding, report sections) can now be saved and reused, and overridden per-report when needed.
2026-04-27 Release 5.4
- MantaWealth - Investment Proposals: a new PDF Report button generates a professionally formatted, client-ready portfolio analysis in a single click — covering allocation, risk metrics, and rebalancing recommendations. Ideal for client meetings, advisory reviews, and compliance documentation.
See a sample output here: Investment Proposal (example PDF).
2026-04-18 Release 5.3
- Release of the MantaRisk MCP Server: AI assistants can now connect directly to MantaRisk to create portfolios, run analytics, and trigger rebalancing.
2026-03-14 Release 5.1
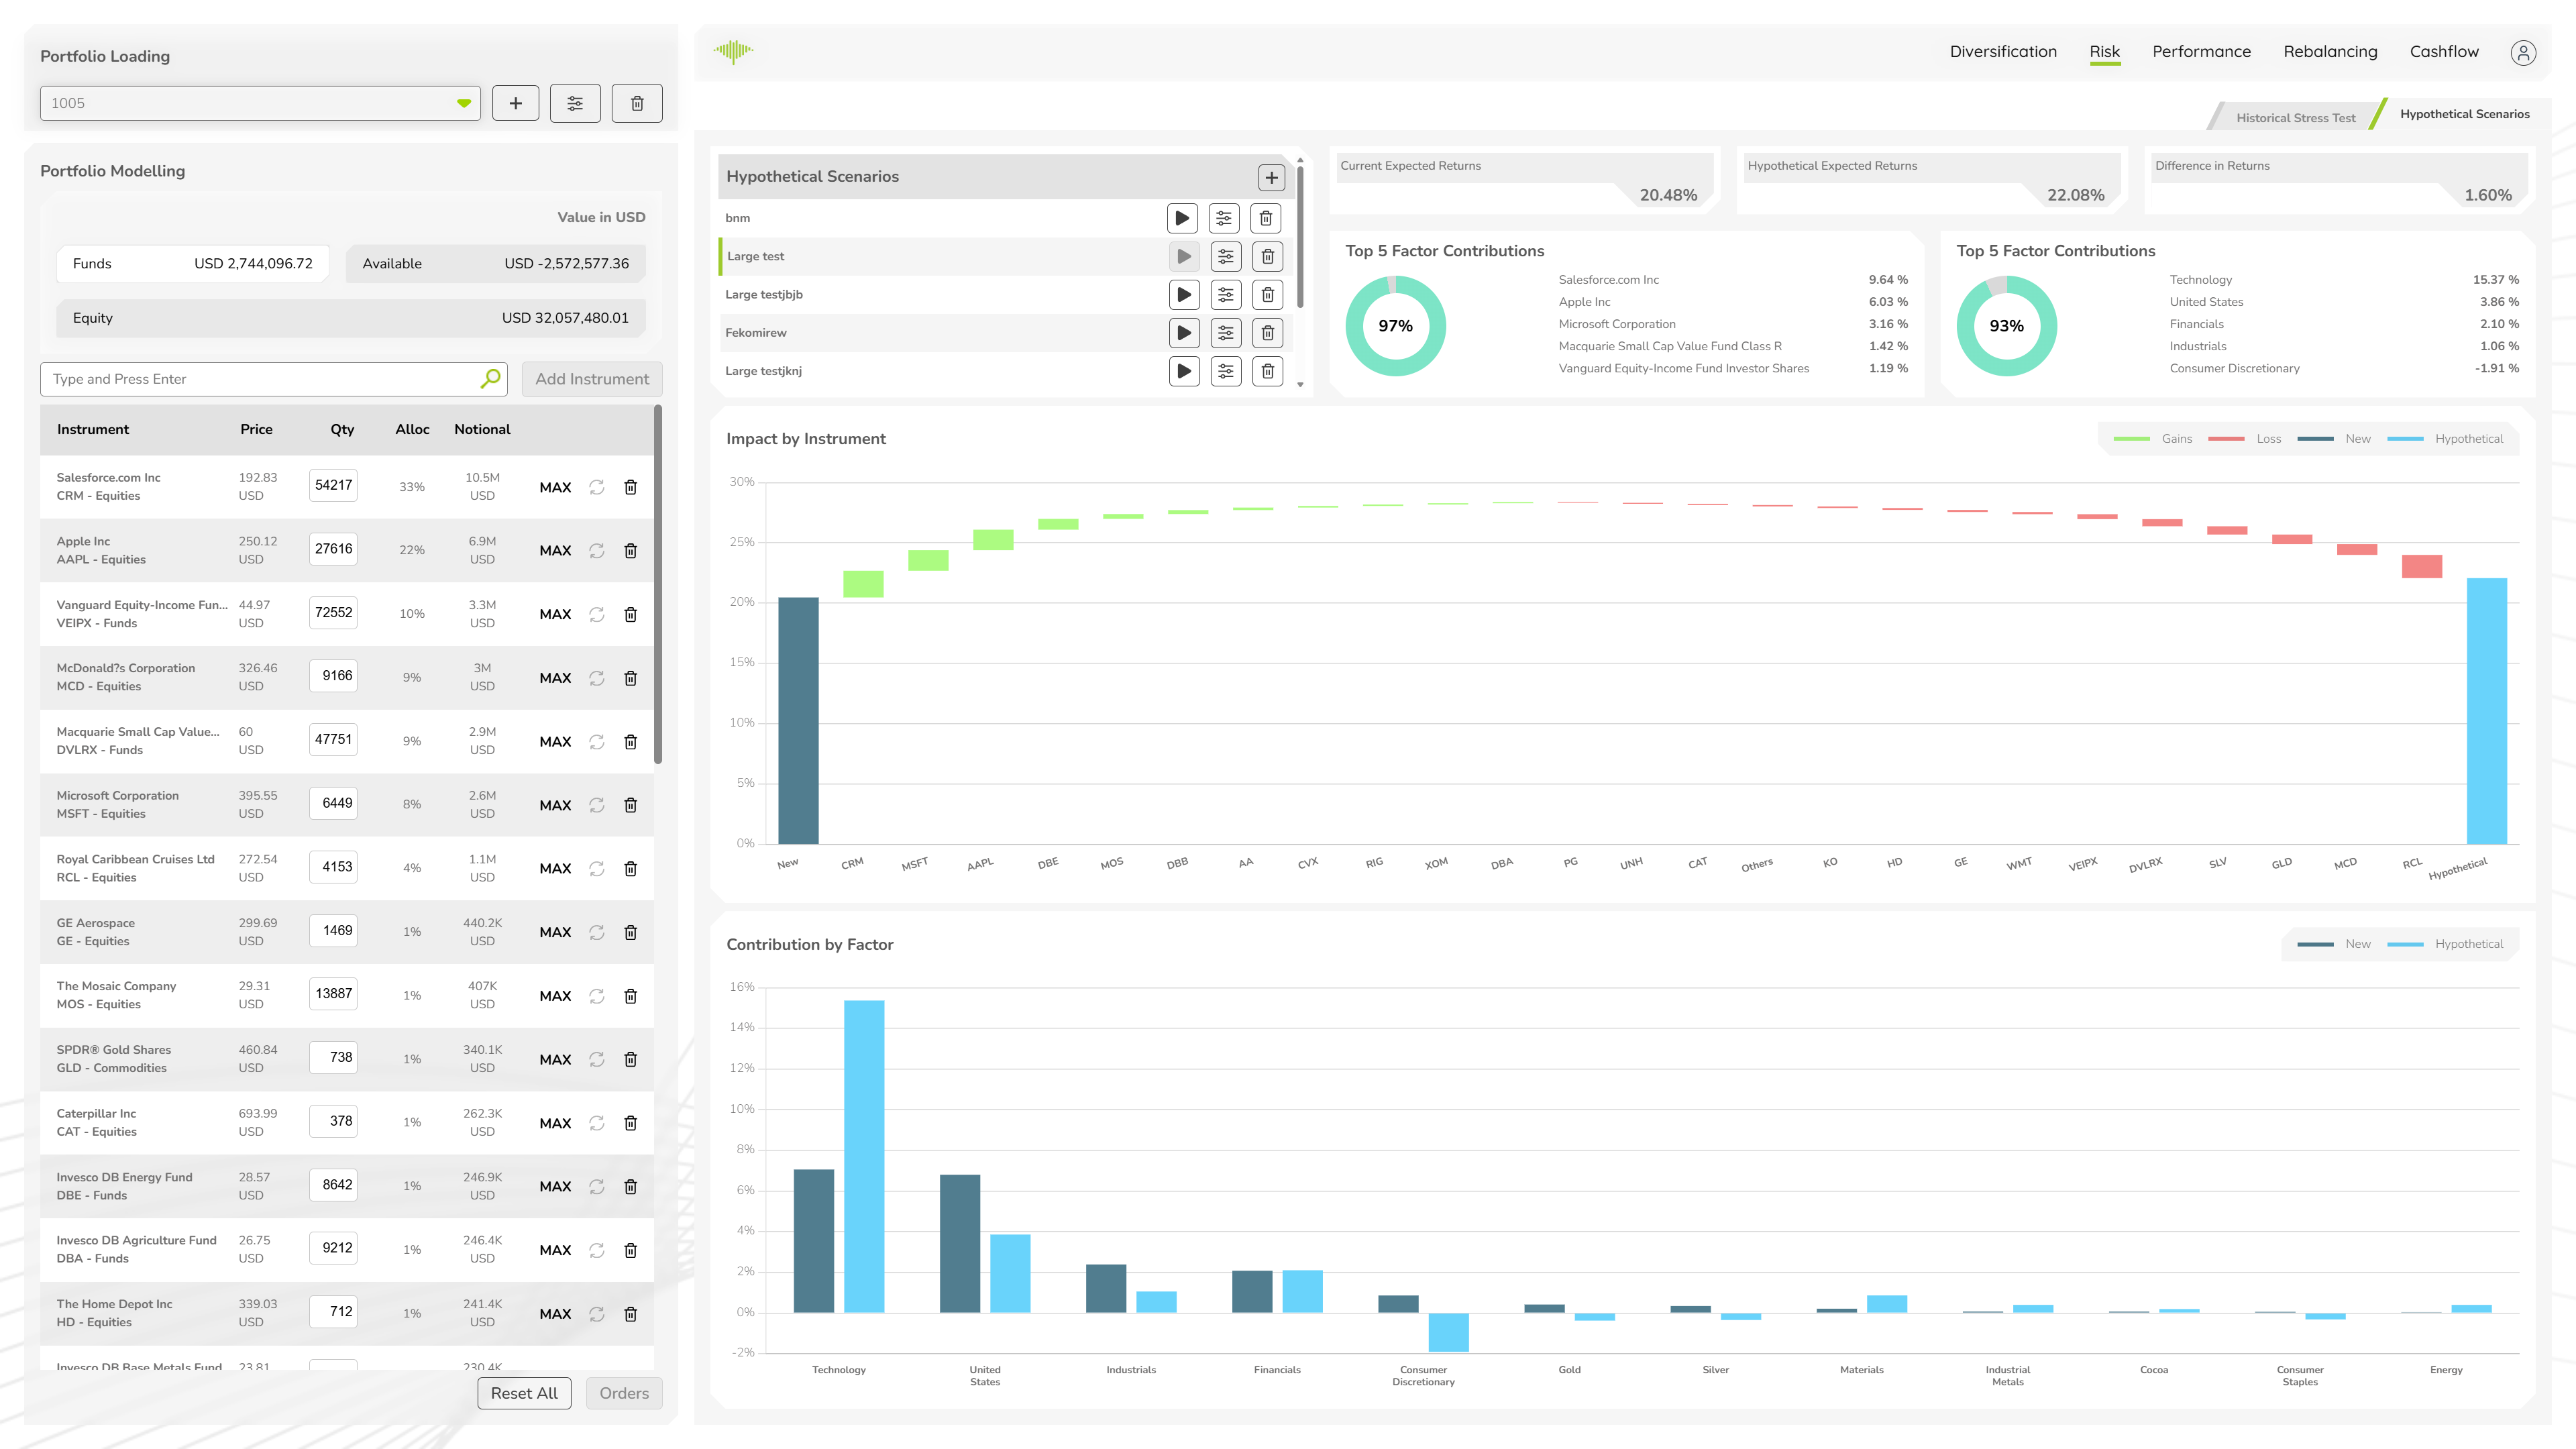
- MantaWealth - Factor based hypothetical stress testing
2026-03-10 Release 5.0
- MantaWealth / MantaAPI - backend performance improvements
- MantaAPI - Factor based hypothetical stress testing
2026-02-21 Release 4.2
- MantaAPI - Coverage for private assets (proxy)
- MantaWealth - UI performance enhancements
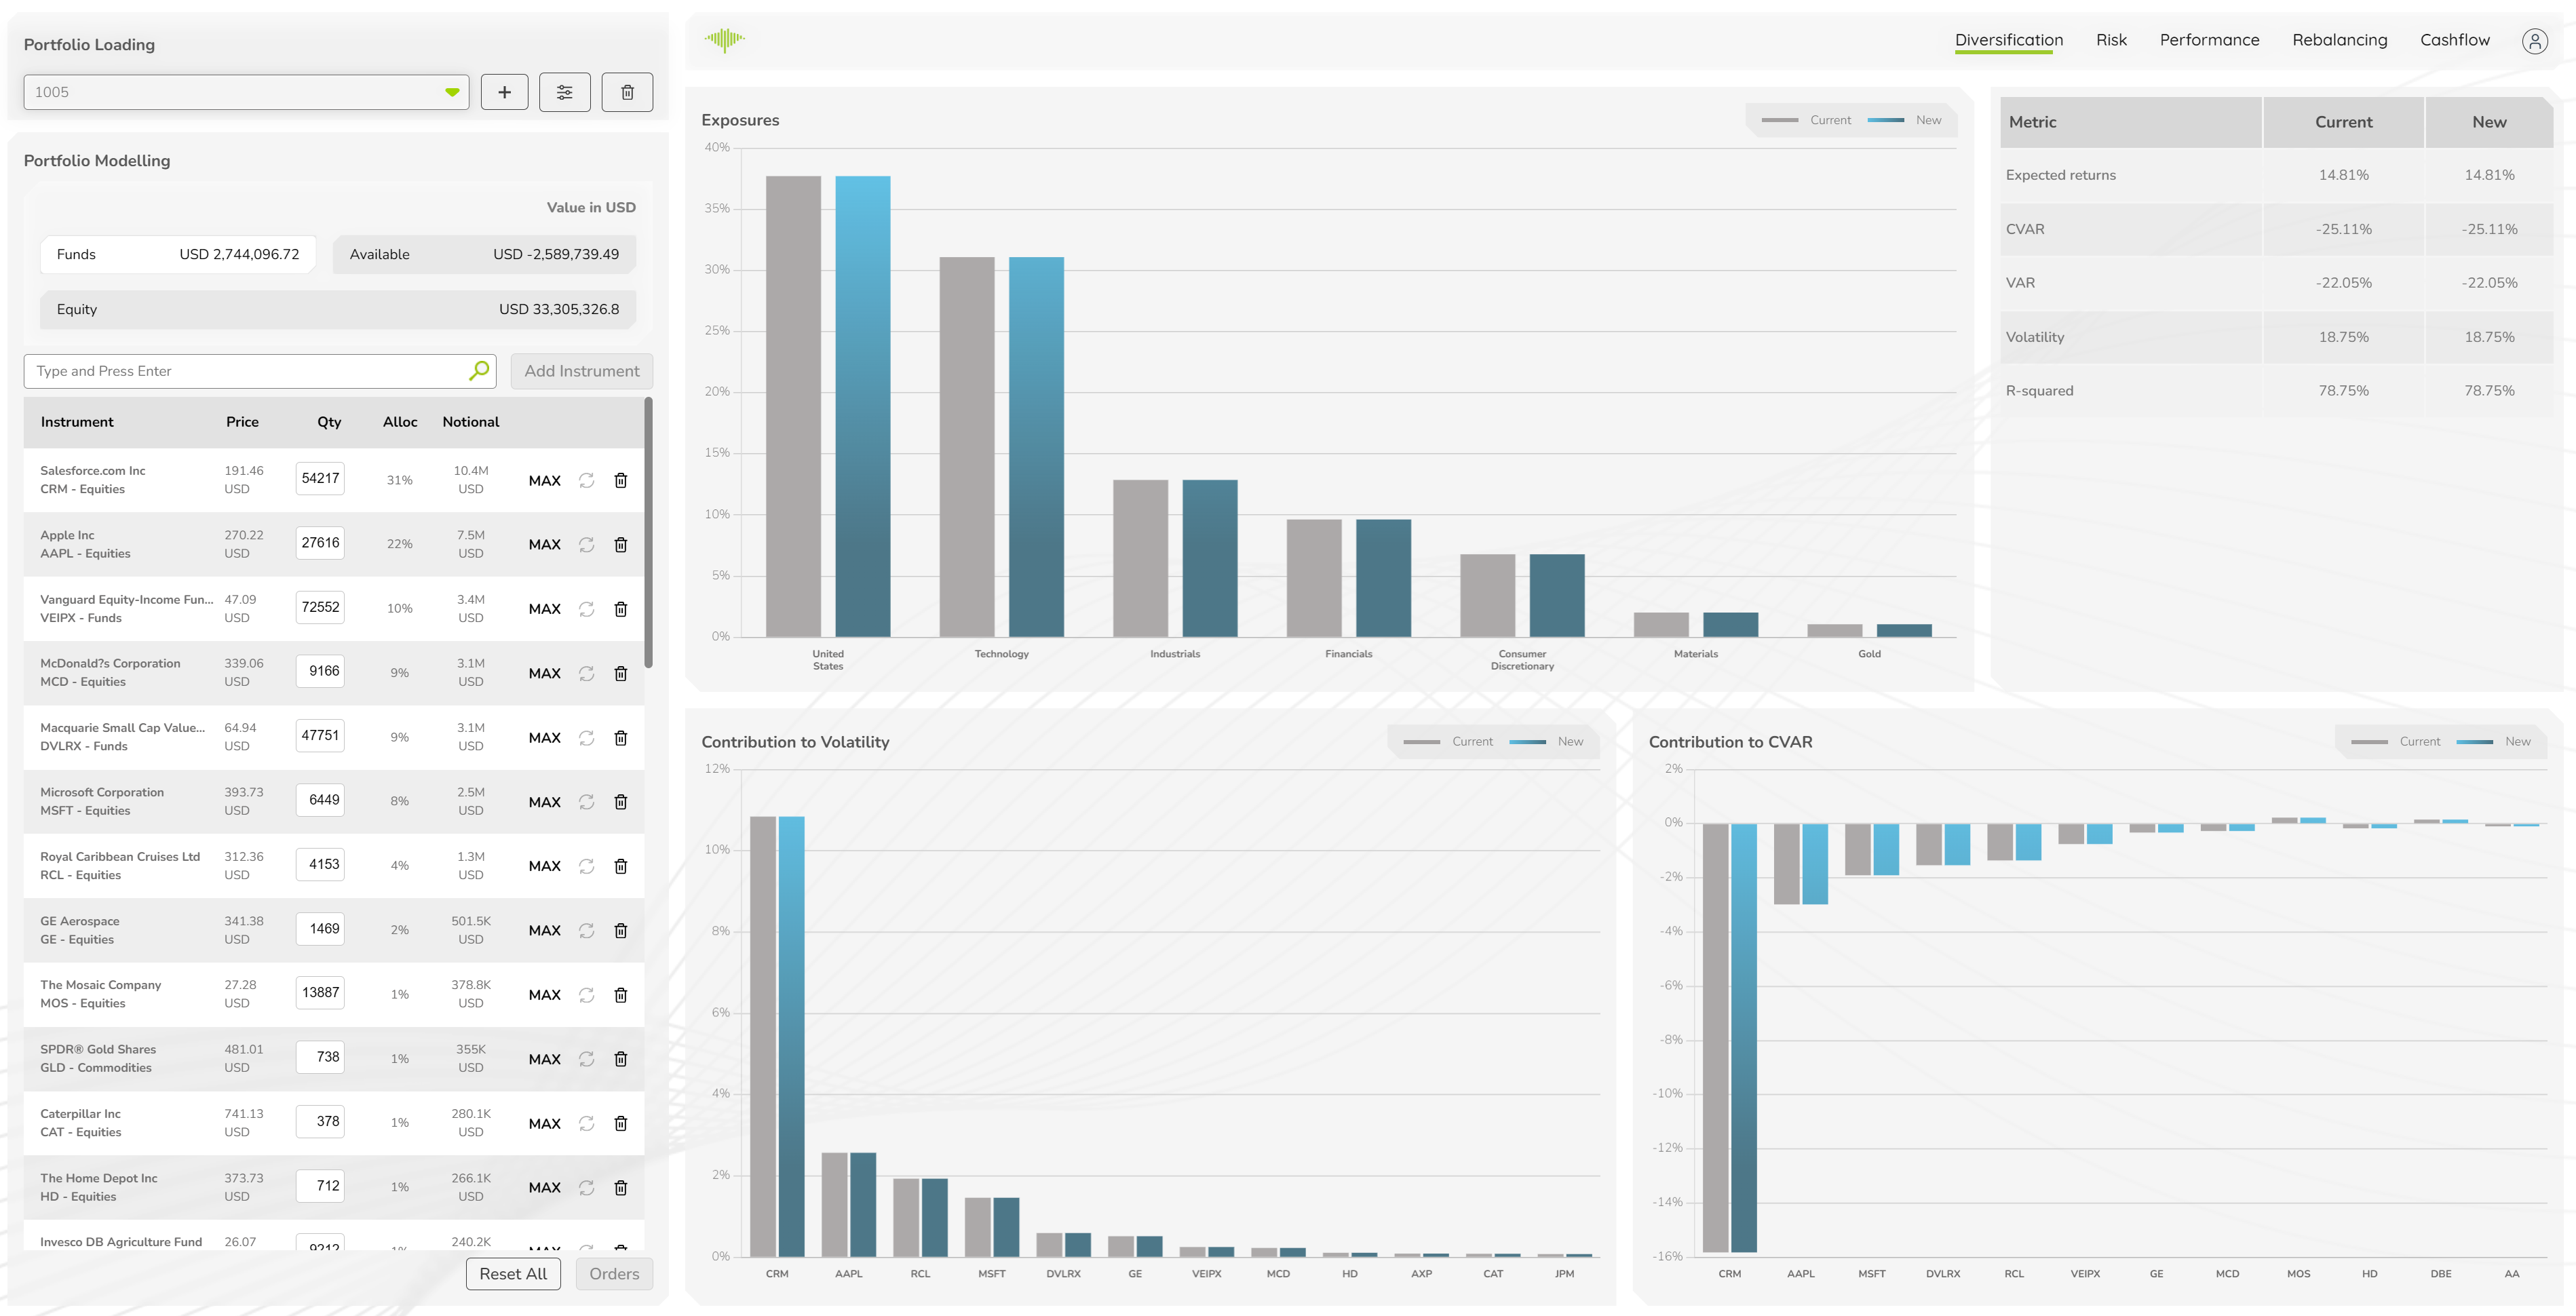
- MantaWealth - upgraded diversification screen
- MantaAPI - support for CUSIPs
- MantaAPI - new endpoint to calculate a portfolio's PnL
- MantaAPI - ability to automatically adjust for dividends and splits on portfolio upload
2025-12-14 Release 4.0
- MantaAPI / MantaWealth - Cashflow forecasting

- MantaAPI - Composite benchmarks made of 2 or more sub-benchmarks
- User configurable asset classifications
- Portfolio Analytics: VaR, CVaR, and expected return aggregated by asset class and sector
- Portfolio Analytics: contribution to portfolio VaR and CVaR broken down by asset class, sector, and individual securities
- Updated billing endpoint with client breakdown for distributors
- Performance Improvements
2025-09-04 Release 3.6
- UI Integration with WealthArc
2025-08-26 Release 3.5
- New /portfolio/benchmark endpoint to correlate an entire portfolio to a specific price curve (alpha, beta, idiosyncratic risk, CVAR). Allows for calculations of exposures to custom factors.
- Faster instrument search functionality
2025-07-26 Release 3.4
Integration with Portfolio Management System Addepar. Our clients can now use their Addepar API keys to have direct access to their portfolios from MantaWealth.
2025-06-16 Release 3.2.6
Update of /analytics endpoint: introduction of additional calculations for expected return:
- Sample based expected returns
- Factor based expected returns
Both are available either equally or exponentially weighted and over daily, weekly and monthly timeframes.
2025-06-03 Release 3.2
- MantaAPI - Backtesting performance improvements
- MantaAPI - Additional equities data coverage
- MantaAPI - New "Data coverage checker" endpoint allowing rapid translation of ISIN / Currency pairs into our instruments.
- MantaAPI - Introduction of Hierarchical Multi Asset Class attribution as an alternative to Brinson Fachler for multi asset portfolios.
2025-03-04 Release 3.1
- MantaWealth - Performance Attribution Analysis UI
- MantaAPI - Performance improvements for loading portfolios
2025-02-23 Release 3.0
- MantaAPI - Short positions
- MantaAPI - Leveraged instruments
- MantaAPI - Coverage and model for Fixed Income
2025-01-30 Release 2.0
- MantaAPI - Performance Attribution Analysis now available. See the API Reference for more details.
2025-01-26 Release 1.4
- All - New account management system: subscriptions can now be directly purchased online through Stripe integration.
- All - Improved historical PnL calculation: PnL is now calculated against historical capital available as opposed to max capital required.
- MantaWealth - Minor UI improvements, security improvements (introduction of single use tokens)
2024-11-22 Release 1.3
- All - Private instances: ability to run our engine privately i.e. within your own architecture
- MantaWealth - Performance improvements
2024-10-14 Release 1.2
- Introduction of pure Maximum Diversification algorithm (Choueifaty and Coignard)
- MantaWealth - Instrument search UI fixes
2024-10-05 Release 1.1
- Introduction of Benchmark Tracking algorithm
- New MantaRisk Website
- Multiple bug-fixes
2024-09-08 Release 1.0
- Release of MantaWealth - our Portfolio Construction Application
- Constraints Based Optimisation: ability to constaint portfolio construction based on geographies, sectors, currencies and individual instruments
- Integration with WealthArc
2024-06-30 Release Candidate 0.5
- Improvements to API health monitor: 2 mins heartbeat, additional tests
- Extensive functional testing pass 2 out of 3 completed
- Backtesting FX conversions issue fixed
- Stale historical data issue fixed
- Improvement in exposure determination
- Alpha caculation now follows Capital Asset Pricing Model
- Performance improvements:
- Historical data for daily timeframe pre loaded
- Exposure pre calculated
- Portfolio Management Application MVP available
2024-06-02 Release Candidate 0.1
- Introduction of API health monitor to ensure fast response from support team
- Extensive functional testing pass 1 out of 3 completed
2024-04-24 Beta 3.2
Publication of new endpoint for portfolio level analytics including:
- Correlation based exposure to sectors, countries and currencies
- CVAR over daily, weekly and monthly periods for the 2.5%, 5% and 10% quantiles
- VAR over daily, weekly and monthly periods for the 2.5%, 5% and 10% quantiles
- Volatility over daily, weekly and monthly periods for the 2.5%, 5% and 10% quantiles
- Diversification ratio: metric used to quantify the level of diversification within a portfolio. MantaRisk uses the definition according to Choueifaty and Coignard (2008) where this ratio considers both the number of assets in the portfolio and the correlations between them. A higher diversification ratio indicates a more diversified portfolio, meaning the assets are less likely to move in the same direction, reducing overall portfolio risk.
- Expected return: defined as the average return over 5 years on a daily, weekly or monthly timeframe
- R Squared: proportion of the variance explained by the risk factors. 1 - R^2 is therefore equivalent to the idiosyncratic risk i.e. the portion of the portfolio which cannot be explained by the risk factors.
2024-04-06 Beta 3.1
- Benchmark endpoint: given two time series (actual and benchmark), provides alpha, beta, idiosyncratic risk etc
2024-03-31 Beta 3.0.1
- Bug fixes (single character instrument search, data source page)
- Increase of the memory pool from 4Gb to 20Gb to allow for large portfolios calculations (500+ instruments)
2024-03-21 Beta 3.0
- Explainable Risk Factors: instrument analytics now provide the exposure of a specific instrument (or price curve) to sectors / countries / currencies
- New API users screen for strategy construction
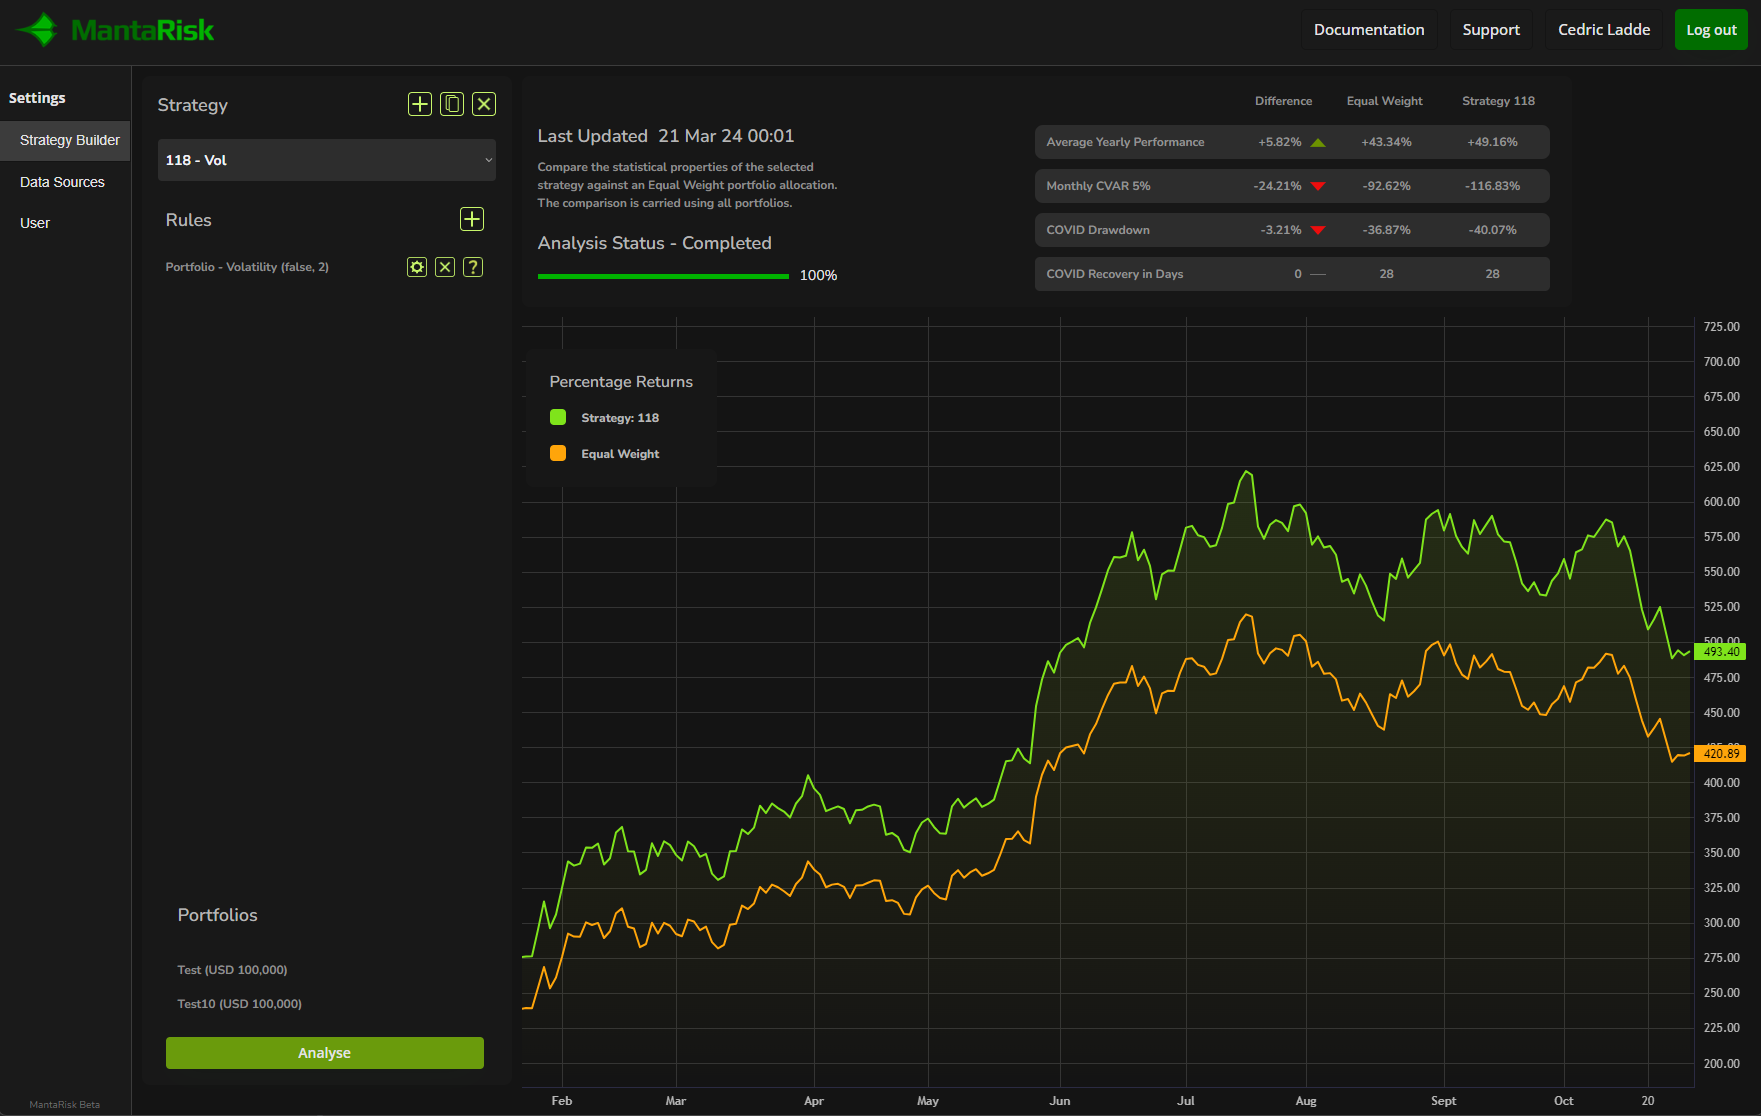
2024-03-04 Beta 2.0.1
New endpoint to provide instrument (or price curve) level analytics. Given a time serie, provides:
- (Correlation based exposure to sectors, countries and currencies) -> next release
- CVAR over daily, weekly and monthly periods for the 2.5%, 5% and 10% quantiles
- VAR over daily, weekly and monthly periods for the 2.5%, 5% and 10% quantiles
- Volatility over daily, weekly and monthly periods for the 2.5%, 5% and 10% quantiles
2024-03-03 Beta 2.0
- New data source added, now covering 162,435 instruments across stocks, forex, crypto, funds, indices and ETFs. Global coverage including EU market at intraday level
- Performance improvements (co-location of services, local instrument search)
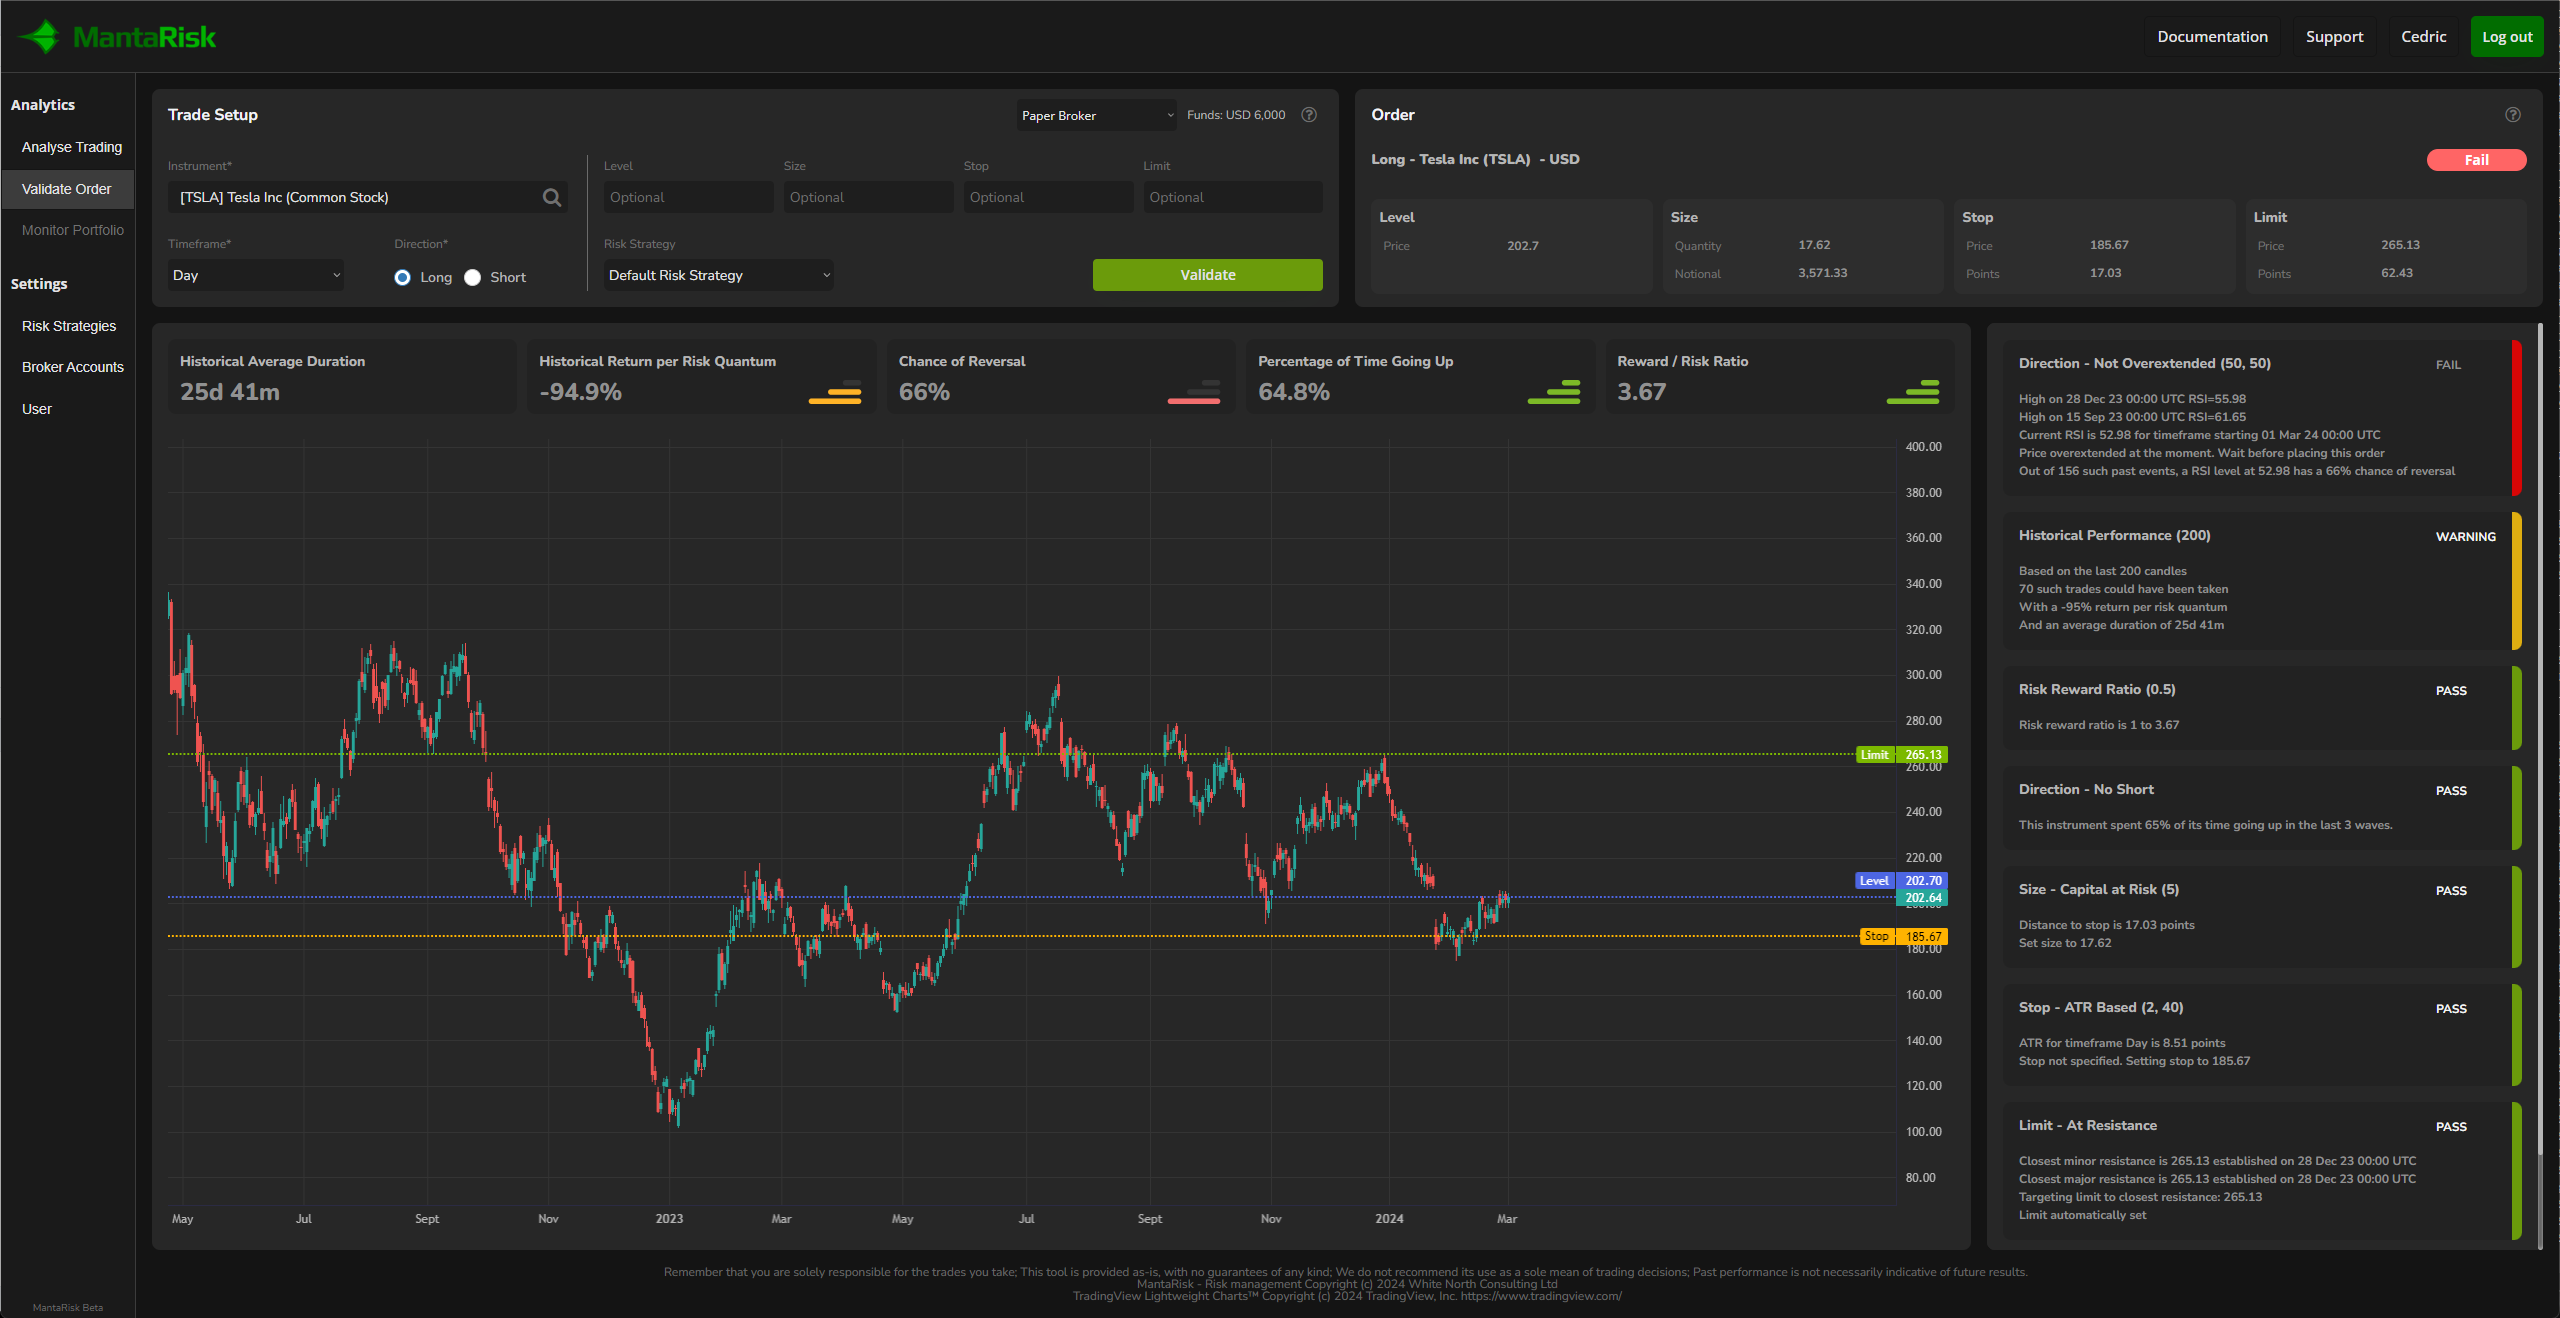
- New Day Trading UI available for Platform users
2024-02-02 Beta 1.9
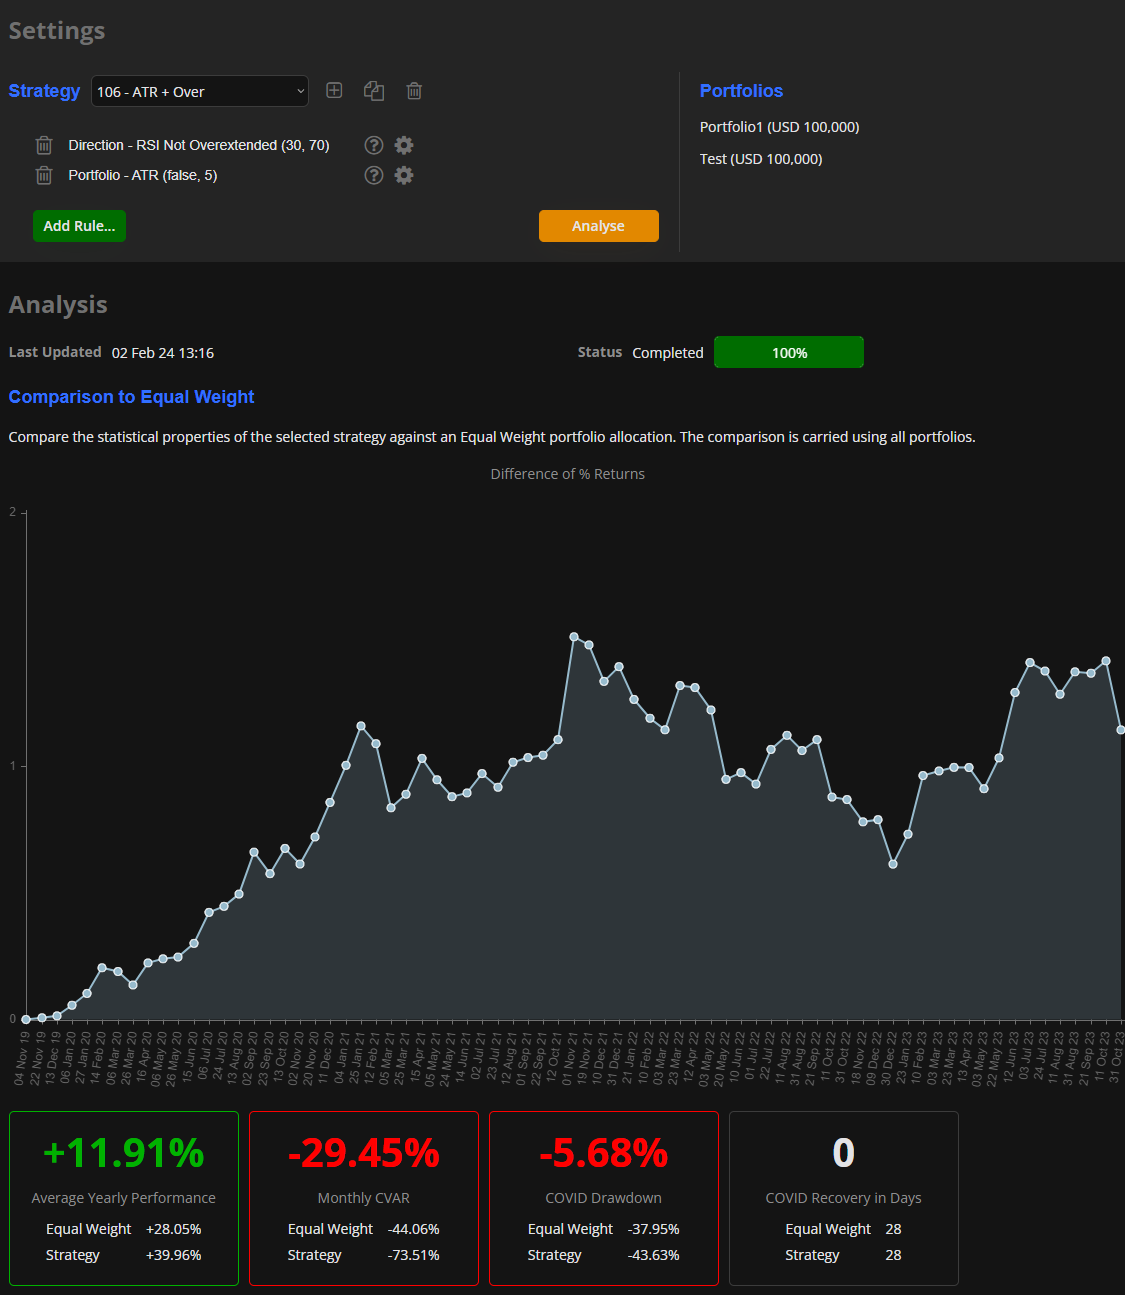
Draft UI to analyse a portfolio management strategy made available to API users.
2024-01-27 Beta 1.8
- Migration of tactical engine to target state infrastructure with high CPU capacity
- Removal of 30 second timeout constraint (504 / H12 error) on all endpoints
2024-01-26 Beta 1.7
- Backtesting performance improvement: migration of the portfolio risk engine to target state infrastructure with high CPU capacity
- Rebalancing methodology tuning - statistical testing of MantaRisk's risk management methodologies has started and has alread led to multiple algorithmic improvements
- Portfolio analysis performance improvement: pre-loading of latest prices
- Various bug fixes
2024-01-07 Beta 1.6
- Release of the Backtesting Engine to allow the testing of risk management strategies for a given portfolio and period of time
- Improvement of Portfolio Analysis (GET /portfolio/analysis) to include advanced rebalancing (reduction of transaction costs caused by high number of trades)
- Introduction of order management within Portfolio Analysis. Open positions can now be added to the portfolio description (PUT /portfolio). These will be taken into account by the portfolio analysis (GET /portfolio/analysis) when suggested orders are sent back.
- Minor performance enhancements
- Various bug fixes
2023-12-17 Beta 1.5
- Release of the ATR portfolio methodology (see Volatility-based Optimization)
- Release of the Risk Parity portfolio methodology (see Volatility-based Optimization)
- Release of the Volatility portfolio methodology (see Volatility-based Optimization)
- Portfolio risk engine performance improvements
- Various bug fixes